When I look at a finance app for gig work, I do not judge it only by whether it can move money. I also ask whether I can understand what is happening quickly, use it comfortably when I am tired or distracted, and recover easily when something needs attention. That is the angle that makes Ualett interesting. It is a free finance app from Cabicash Solutions, Inc., built around the needs of people whose income may arrive through flexible or independent work rather than a traditional payroll schedule.
I approached Ualett as a tool for everyday cash-flow management, not as a complete replacement for a bank, tax adviser, or budgeting system. That distinction matters. A gig worker may need access to money between jobs, a clearer view of incoming funds, or a simpler way to manage work-related finances. At the same time, anyone considering it should think about how much financial detail they need, how comfortable they are with mobile-only tasks, and whether the app fits their particular work arrangement.
How Ualett feels to use in everyday situations
Readable navigation matters more than flashy finance features
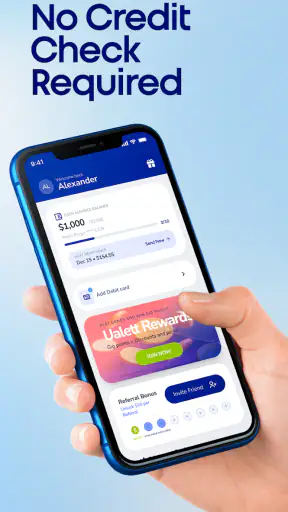
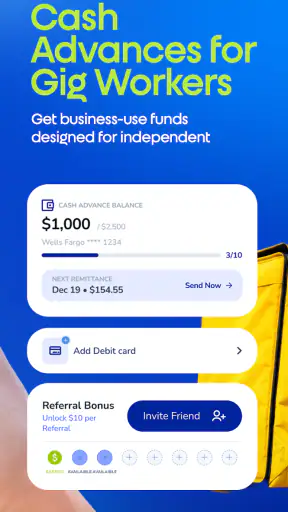
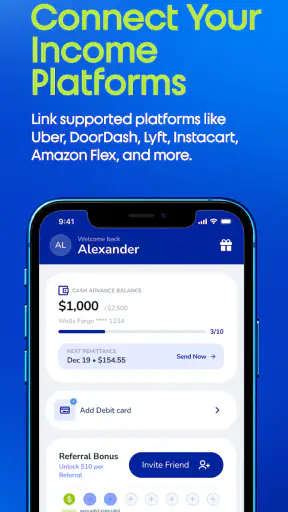
The strongest first impression of a finance app is often not a special feature. It is whether the main screen helps me answer basic questions without making me hunt: what is available, what is pending, and what action should I take next? Ualett’s identity as a gig-worker-focused app gives it a more specific purpose than a general banking application. That focus can make the experience feel less overwhelming for someone who mainly wants to manage work-related cash flow.
I find that this kind of focused design is particularly useful when I am checking an account during a short break between deliveries, rides, appointments, or freelance tasks. I do not want to study a wall of financial categories at that moment. I want the important information to be recognizable, with actions separated clearly enough that I do not tap the wrong option while moving quickly.
There is also a practical benefit for people who are not confident with financial terminology. A gig-worker account can be easier to approach when its purpose is explained in ordinary language rather than through banking jargon. That does not remove the need to read transaction details carefully, but it can reduce the mental effort involved in getting started.
My advice is to spend time exploring the main screens before relying on the app during a busy workday. Open each visible menu, identify where account information and support options live, and learn the difference between available funds and money that is still processing. This is a small preparation step, but it is more valuable than assuming every balance number means the same thing.
Useful for short checks, less ideal for detailed financial planning
Ualett makes the most sense when I treat it as a quick-access financial tool. A person who needs to check a work-related balance several times during the day may appreciate a focused mobile experience more than a broad banking app filled with savings, investment, loan, and household features. The narrower purpose can be a strength because fewer unrelated choices may stand between the user and the task.
That same focus creates a trade-off. If I want a full monthly budget, detailed spending analysis, long-term savings goals, or an all-in-one view of several financial institutions, a traditional banking app or dedicated budgeting service may be better. Ualett should not be expected to replace every financial tool simply because it sits in the finance category.
This is one of the most important decisions for a potential user: do you need a work-income companion or a complete personal-finance dashboard? For the first need, the app’s purpose is easier to understand. For the second, adding another app may create more work rather than less, especially if I must move information manually between services.
Accessibility begins with reducing mental load
When people talk about accessibility, they often focus only on screen readers or font size. Those details matter, but cognitive accessibility matters too. A worker checking finances after a long shift may have limited attention. Clear labels, predictable navigation, and a small number of relevant choices can make the difference between finishing a task and abandoning it.
Ualett’s gig-worker orientation can support that kind of use because the app is not trying to speak to every possible banking customer at once. I would still recommend reading each confirmation screen rather than relying on icons or assumptions. Financial actions deserve a slower final check, even when the surrounding interface feels simple.
For users who prefer larger text, stronger contrast, spoken feedback, or switch-based navigation, the experience will depend partly on how the app works with the accessibility settings already available on the phone. I would test those settings before depending on Ualett for urgent tasks. A finance app can be conceptually simple and still become difficult if important labels are cramped, controls are too close together, or status messages disappear quickly.
Motor and sensory considerations during real work
Gig work often happens in less-than-ideal conditions. I may be standing outside, wearing gloves, carrying bags, riding as a passenger, or using a phone with one hand. Those situations change what “easy to use” means. A good workflow should not require delicate tapping or repeated navigation when my attention is divided.
Ualett is best used when I can stop safely and give the screen my full attention. I would not try to complete a financial action while driving, walking through traffic, or handling a customer order. This is not a criticism unique to Ualett; it is a sensible boundary for any app involving money. The relevant question is whether the app lets me finish a task quickly once I have paused.
Users with limited dexterity should pay attention to how comfortable the main controls feel on their own device. Screen size, operating-system settings, and touch sensitivity can change the experience considerably. If repeated tapping, scrolling, or precise selection becomes tiring, using the phone’s built-in magnification or larger display options may help, but I would verify that every important control remains visible and usable afterward.
For users with sensory sensitivities, a calmer workflow is preferable to constant checking. I would turn off nonessential phone notifications if they become distracting and choose a regular time to review activity. The goal is to avoid letting a finance app interrupt every part of the workday while still checking important changes promptly.
Situational access for gig workers
The app’s clearest audience is someone with flexible income and a need to manage money around work rather than around a fixed payday. Imagine finishing several jobs in the afternoon, needing to check whether funds are available before paying for fuel, and wanting to keep work-related money separate from household spending. A focused tool can make that routine easier to organize, provided the user understands what each balance represents and does not treat pending funds as spendable cash.
Another realistic use is planning around irregular hours. A worker may have a strong day followed by a quiet one, so the useful question is not simply “how much did I earn?” but “what can I safely use now, and what needs to remain available for the next shift?” Ualett can fit into that kind of check-in, but I would still keep a separate record for expenses, taxes, mileage, or other deductions if those details matter to my work.
This is where the app should be paired with a habit rather than used in isolation. After a work session, I would review the account, note the amount that is genuinely available, and record relevant expenses in a separate budgeting or bookkeeping method. That two-step routine prevents a convenient cash-access tool from becoming an incomplete accounting system.
Situational access also includes connectivity, battery life, and privacy. A worker may need to use the app away from home, so I would avoid making urgent financial decisions in a place with an unstable connection. I would also use a device lock and avoid displaying account details where customers or passersby can see them. These precautions are simple, but mobile finance is safest when convenience does not override basic privacy habits.
Where it compares well with usual alternatives
Compared with a standard bank app, Ualett has a more defined relationship with gig work. A general bank may offer broader tools, but those tools can bury the specific task I need under features for loans, cards, savings, transfers, and household accounts. Ualett may feel more approachable when my main concern is work-linked access and a straightforward mobile routine.
Compared with a budgeting app, the difference is even clearer. Budgeting software is usually strongest at categorizing spending, setting limits, and showing patterns over time. Ualett is more relevant to the immediate movement and handling of gig-related funds. I would choose the budgeting app when I need a long-term financial picture and Ualett when I need a more direct work-income workflow.
Compared with keeping everything in one personal checking account, a dedicated gig-worker-oriented option may help create a mental boundary between earnings and ordinary spending. That separation can be useful for people who otherwise spend work income before accounting for fuel, supplies, taxes, or upcoming bills. The trade-off is managing another financial destination and remembering to review it regularly.
No alternative is automatically better. A conventional bank may be preferable for someone who values branch access, a wide range of account products, or an established relationship with one institution. A spreadsheet may be enough for someone who only needs a manual record. Ualett is most convincing when its focused purpose solves a real daily problem rather than simply adding another app to the phone.
Remaining barriers and points that deserve caution
The main limitation I see is that simplicity can hide important distinctions. A clean interface may encourage quick decisions, but financial timing is not always simple. Available, pending, deposited, and transferable amounts can have different meanings. I would never make a rent, fuel, or bill payment based only on a glance at the first balance I see.
There is also a learning curve for people who are new to app-based finance. Even if the navigation is approachable, users still need to understand account activity, confirmation messages, and any conditions attached to moving money. I recommend reading the first few transactions carefully and saving support information somewhere accessible before an urgent problem occurs.
People who rely on assistive technology should test the complete journey, not just the opening screen. The important question is whether they can sign in, inspect activity, understand status messages, and complete a financial action without assistance. If one stage is difficult, that may be a serious barrier even when the rest of the app feels clear.
Language and financial confidence can create additional friction. A user who is comfortable with everyday phone apps may still feel uncertain when a money-related message uses unfamiliar wording. I would not guess at the meaning of an alert. Taking a screenshot for personal reference, enlarging the text, or asking a trusted person to help interpret it is safer than approving an action I do not understand.
The app’s age rating is Everyone, which makes its broad audience easy to understand, but age suitability does not automatically mean every user will find the financial workflow equally accessible. Younger users, older adults, people with disabilities, and workers with limited digital experience may need different kinds of support. The most inclusive approach is to let each person test the tasks they actually need rather than assuming a general rating settles the question.
What the current app details suggest
Ualett was released on August 21, 2018, and its current version is 2.73.0. It supports Android 8.0 and later, so compatibility is worth checking before planning a switch from an older phone. I appreciate that the version information is clear enough to make that initial decision, especially for workers who keep an older device as a backup.
The app is free to install, which lowers the barrier to trying it. Free access is helpful for gig workers who are already managing variable income, but I would still read every in-app explanation connected with a financial action. “Free” describes the app’s price, not necessarily every possible cost associated with using a financial service, moving money, or relying on another institution. Careful reading is part of responsible use.
Its public response is encouraging: Ualett has an average rating of 4.6 from around 7.6 thousand ratings, with roughly 1.3 thousand written reviews and over 500 thousand installs. Those figures suggest that many people have found a reason to keep using it, although ratings cannot tell me whether the app suits my exact work type, device, or accessibility needs. I treat them as a useful signal, not a substitute for testing the workflow myself.
Who should try it, and who should skip it
I would recommend trying Ualett if you earn through gig work, prefer handling finances from a phone, and want a tool with a more focused purpose than a conventional bank dashboard. It is also worth considering if separating work-related money from ordinary spending would make your routine easier to understand.
I would be more cautious if you need full bookkeeping, detailed tax preparation, advanced spending reports, or a single place to manage several financial products. In those cases, a bank app, budgeting service, accounting tool, or combination of services may be more suitable. Adding Ualett could still help with a narrow task, but it should not be mistaken for a complete financial command center.
I would also skip it, at least initially, if I cannot comfortably read and confirm financial information on my current device. A larger screen, updated operating system, or help from a trusted person may be necessary before any mobile finance app becomes practical. Accessibility is not an optional extra when the app controls access to money.
My inclusive verdict
Ualett is a sensible option for gig workers who want a focused finance app rather than another general-purpose banking dashboard. In my view, its strongest quality is the way its purpose can reduce clutter for people managing irregular work income. That focus may support quicker, less stressful check-ins, especially when I have already learned where the important information lives.
Its inclusive value depends on the details of each person’s device, abilities, and work environment. The app can support situational access when I pause safely, use readable display settings, and build a routine around checking available funds instead of rushing through alerts. It is less suitable when I need extensive financial analysis, complex bookkeeping, or a workflow that has not been tested with my assistive settings.
My practical recommendation is to install it, explore the navigation without making an urgent transaction, and test the exact tasks you expect to perform. Check whether you can read balances, understand activity, locate help, and complete a confirmation comfortably. If those steps feel clear, Ualett may become a useful part of a gig-work routine. If they do not, a traditional bank or a more specialized budgeting tool may serve you better. The best choice is the one that makes your money easier to understand without creating a new accessibility barrier.


